

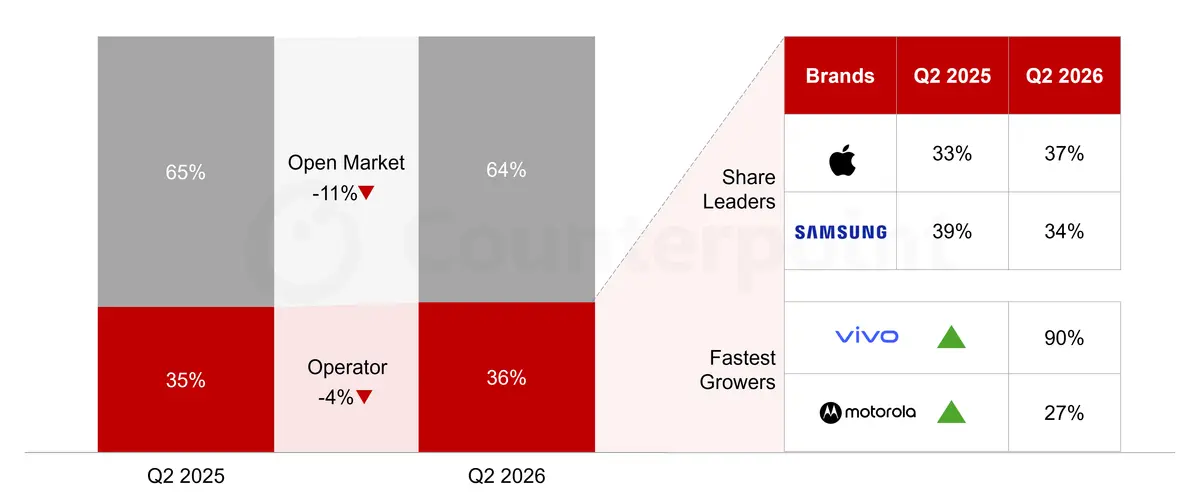
- The operator channel has gained share in the European smartphone market in 2026. While total smartphone sales declined by 8% YoY in Q2 2026, sales through operators declined by 4%, resulting in share gain versus the open market which declined by 11%.
- Smartphone sales through operators are typically more high-end than through the open market, as more are purchased on a contract. The collapse of the low-end of the smartphone market so far in 2026 because of the memory price crisis has therefore benefitted the operator channel.
- Apple overtook Samsung and became the share leader of the European operator channel in Q2 2026. Meanwhile, Motorola and vivo grew the fastest YoY. This was a change from Q2 2025 when Google and HONOR were the fastest growing OEMs through the operator channel.
- Operator channel sales are likely to continue to gain share versus the open market over the next few quarters as the lower end of the market continues to be impacted by the memory crisis, despite a steady increase in promotional activity by independent retailers.
Beijing, Berlin, Buenos Aires, Fort Collins, Hong Kong, London, New Delhi, Seoul, Taipei, Tokyo – October 6, 2026
The European smartphone market has been shifting slowly in favour of operators so far in 2026. While total smartphone sales declined by 8% YoY in Q2 2026, sales through operators declined by only 4% YoY, resulting in share gain compared with the open market which declined by 11% YoY, according to the Counterpoint Research Europe Channel Share Tracker. Apple was a key driver of this shift, having overtaken Samsung as the market share leader of Europe’s operator channel. Motorola and vivo also contributed to the growth with some strategic positioning with key European operators.
Europe Smartphone Sales Share by Channel
Source: Counterpoint Research Europe Channel Share Tracker
Associate Director Jan Stryjak said, “Smartphone sales through operators in Europe are typically more high-end than through the open market, as more are purchased on a contract. They are also more skewed towards more premium brands like Apple, Samsung, and Google. The collapse of the low-end of the smartphone market so far in 2026 because of the memory price crisis has therefore benefitted the operator channel, which has declined comparatively less than the open market.”
Stryjak added, “We expect operator channel sales to continue to gain share versus the open market over the next few quarters as the lower end of the market continues to be impacted by the memory crisis. However, we are seeing a steady increase in promotional activity by independent retailers compared to operators, which could mitigate some of the price rises and provide addition stimulus to the open market.”
About Counterpoint Research
Counterpoint Research is a global market research firm specializing in products across the technology ecosystem. We advise a diverse range of clients – from smartphone OEMs to chipmakers and channel players to Big Tech – through our offices located in the world's major innovation hubs, manufacturing clusters and commercial centers. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation.
Follow Counterpoint Research

